Spreads narrow on SoFi’s 1st consumer loan ABS of 2018
The deal was launched shortly after SoFi announced that Anthony Noto, the chief operating officer of Twitter, will join as CEO. It also benefits from higher credit enhancement.

© 2026 Arizent. All rights reserved.

The deal was launched shortly after SoFi announced that Anthony Noto, the chief operating officer of Twitter, will join as CEO. It also benefits from higher credit enhancement.
The online lender to small businesses is expanding its business deeper into traditional banks’ territory with larger loans.
David Nelms said that many digital lenders do not understand how to underwrite personal loans properly, and he took a dig at their lack of profitability. The upstarts say their industry's ability to attract capital speaks for itself.
StreetShares seeks to tap into the loyalties of military veterans, bringing together borrowers and savers through an online platform.
Stepping in after co-founder Mike Cagney's resignation, Twitter's Anthony Noto needs to overhaul the firm's corporate culture, lay the groundwork for an IPO and determine whether to renew SoFi's pursuit of a bank charter.
Marketplace lenders bringing securitization in-house seized the top spot in 2017; readers also focused on Blackstone's big entry into an esoteric corner of the CRE market and the PACE industry's embrace of consumer protections.

Intrust Bank has agreed to purchase $20 million worth of Funding Circle's small-business loans in what could just be the beginning of a long-term relationship.
By sponsoring their own deals these matchmaking platforms are providing liquidity to multiple loan investors. They can also ensure that bond offerings are regular and uniform.

Some were sold at discounted prices, while others were shut down by their acquirers or quietly ceased doing business.
The court decision regarding the “valid when made” doctrine moved us further away from creating a more effective and inclusive financial system.
The prime consumer loans backing the $330M CLUB Credit Trust 2017-P2 transaction include a greater percentage of higher-FICO borrowers.

The British banking giant has been testing its new online lending platform with a handful of its U.S. customers and plans to roll it out in full force next year. It's all part of a broader effort to expand its U.S. consumer business beyond credit cards.
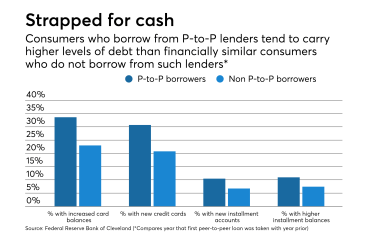
Fed researchers purported to show that consumers who use peer-to-peer loans have bad financial outcomes, but questions quickly emerged about the data they used.
Consumers who have borrowed from online lenders owe more and have lower credit scores than similarly situated consumers who have not used online lenders, according to a study released Thursday by the Cleveland Fed. The provocative findings seem likely to spark intense debate.
Four tranches of rated notes totaling $591 million were issued, resulting in an advance rate of 92% vs 88% for the previous deal; pricing also improved.

The San Francisco firm is the latest U.S. lender to tighten credit standards amid concerns that consumers are shouldering too much debt.
The San Francisco-based lender still posted losses in its portfolio, although those declined considerably from the year-ago period.
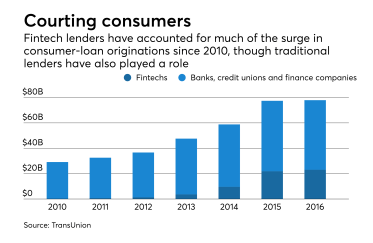
Amid the rise of online lending earlier this decade, banks were derided as being too slow to adapt. But over time it's become clear that banks hold key advantages over lending startups.
British regulators are touting the success of their so-called regulatory sandbox. Their American counterparts have been unable to agree on a comprehensive scheme to foster innovation.
Fitch and KBRA have slightly lower estimates for cumulative net losses for 2017-3, allowing the marketplace lender to offer slightly lower credit enhancement on the senior notes; concerns remain about poorly performing legacy loans.

Couldn’t load more articles. Try again.