B of A: Agency MBS issuances to decline by 16% in 2027
Persistently high mortgage rates will shrink securitization volume by dampening home sales and pushing more buyers toward all-cash purchases.
© 2026 Arizent. All rights reserved.

Persistently high mortgage rates will shrink securitization volume by dampening home sales and pushing more buyers toward all-cash purchases.
Some current residential mortgages could face higher capital charges, prompting a shift into securitization portfolios.

More than 80% of the mortgage pool was originated utilizing alternative or non-traditional income documentation, KBRA said.

Self-employed borrowers represent just 23.1% of the pool, and liquid reserves were $858,428 compared with 21.9% and $1 million.
Certain private-label securities may get a lower risk weighting for bank capital and separately, second liens have new uniform guidelines for TRID.
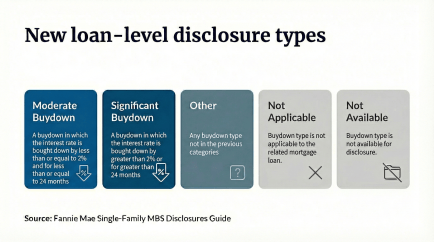
Fannie Mae and Freddie Mac will add loan-level buydown data to MBS this spring, giving investors clearer insight into prepayment risk tied to temporary rate incentives.
Alternative asset manager Canyon Partners is committing $250 million to buy new mortgage bonds created by A&D Mortgage LLC, a partnership that will help the mortgage finance company substantially increase the pace of its bond sales.
Brookfield Asset Management and a private equity partner reached a friendly deal to take over First National Financial Corp., a mortgage company backed by Canadian billionaire Stephen Smith, for about C$2.9 billion ($2.1 billion).

On a cumulative basis, advance rates on the notes range from 95.4% on the A1 notes to 121.8% on the class M5 notes.
The transaction's pool of 365 fixed-rate mortgages, all first lien, breaks down to mostly non-agency loans (61.4%). The rest, 38.6%, are agency eligible.

The funding round will help Button Finance, which leverages AI to underwrite home equity financing, expand its range of products to more borrowers.
Mortgage bonds supported by government-backed companies like Fannie Mae and Freddie Mac were trading slightly wider Monday morning after Moody's Ratings downgraded the US late last week.
A range of investment residential properties, including single-family homes, condominiums and multi-unit properties, will secure the debt.
Moderate leverage is one example of cleaner credit, as the current collateral pool's original loan-to-value (LTV) ratio is 69.1%, down from 71.7% on the 2024-NQM1 series.
Originators applied bank statement, full documentation and profit and loss documentation in their underwriting.

The deal is composed of 11,547 seasoned performing and reperforming loans that are first and second lien. Loan servicing includes a 180-day chargeoff feature.

Second-lien loans make up virtually the entire pool, which carries some risk of poor recovery rates. Yet 78% of the pool is also considered safe-harbor mortgages.
Now the structured mortgage securities are cheap enough that CLO investors are watching them more closely, according to strategists and investors.
Excess cash flow will pay timely interest and protect against realized losses in the rated certificates before being paid out to the class X notes.
Small-balance commercial mortgages, SBA 504 and investor loans, all first-lien, make up the collateral pool.

Couldn’t load more articles. Try again.