
Impac Mortgage Holdings’ nonqualified mortgage origination volume increased 248% year-over-year in the third quarter as the company accumulates loans for a planned securitization next year.
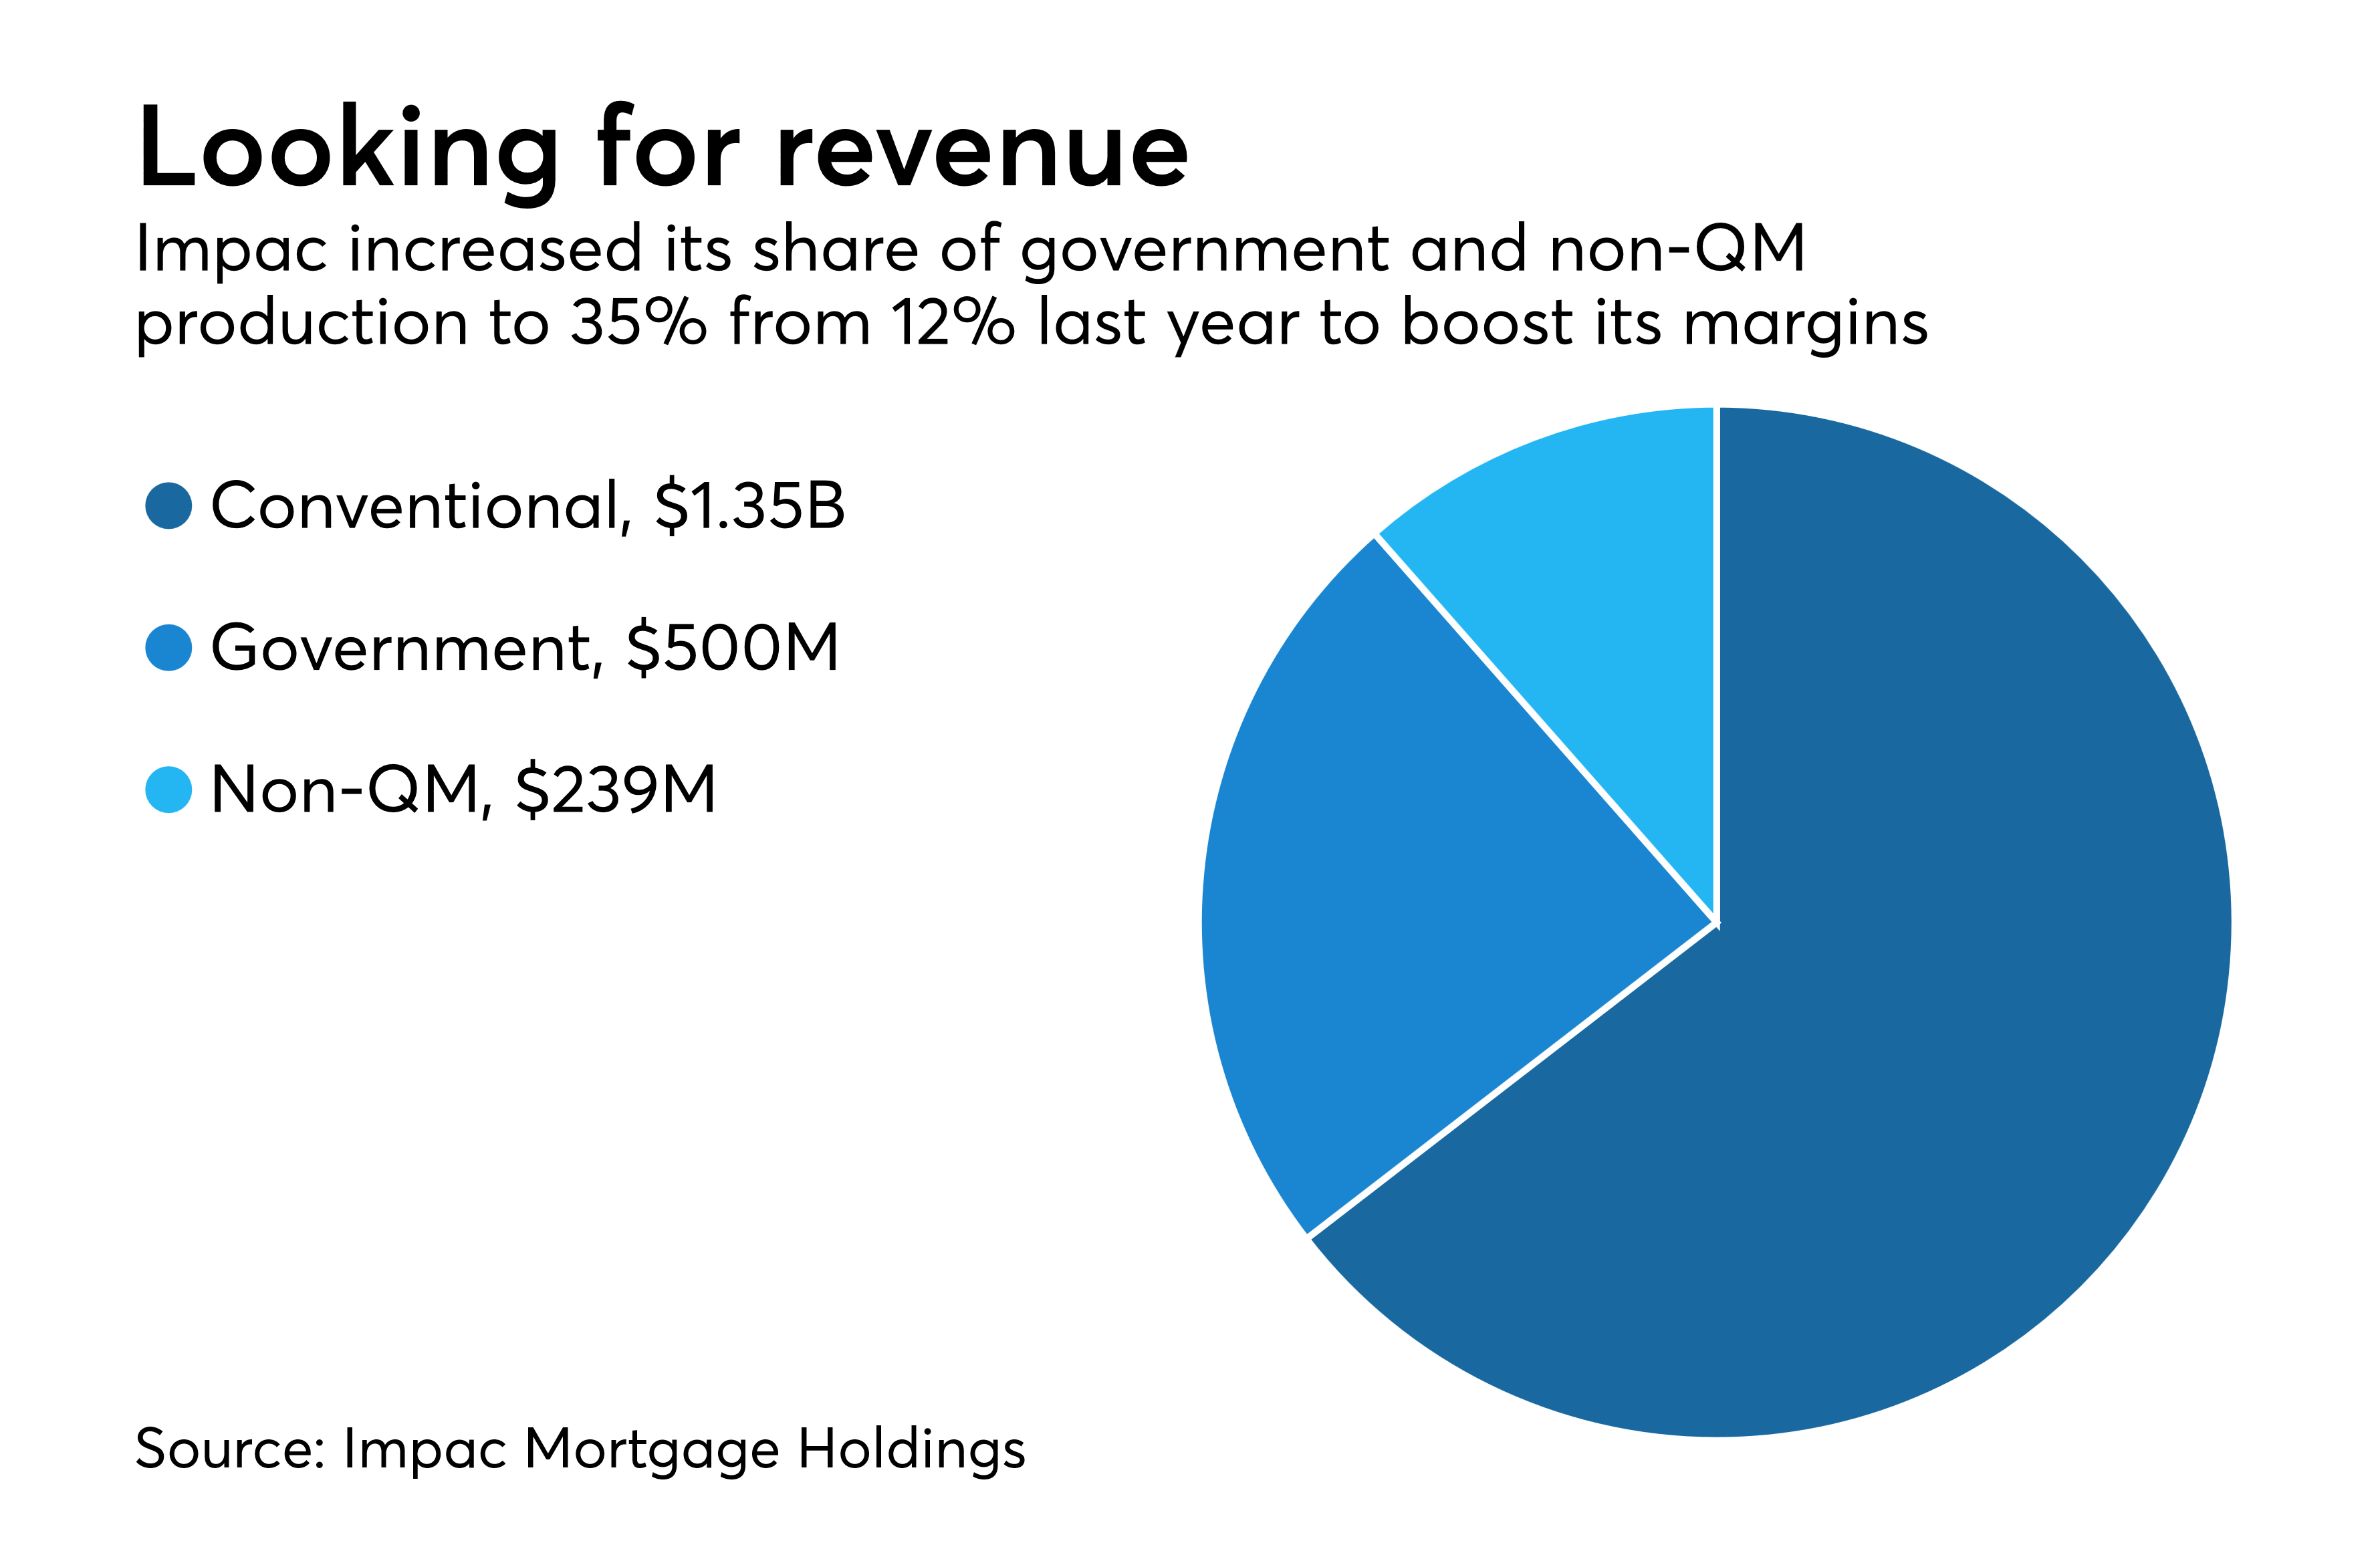
Because they are higher-margin products, Impac has emphasized growing non-QM production and government loan originations. Combined, these products made up 35% of its total originations of $2.1 billion for the third quarter. Last year, Impac originated $4.2 billion in the third quarter.
The retail channel produced $1.4 billion, with correspondent adding $376 million and wholesale contributing $282 million.
In April, Impac sold $56 million of common stock to capitalize the growth and eventual securitization of non-QM originations.
The Irvine, Calif.-based mortgage banker originated $239.4 million of non-QM loans during the third quarter, compared with $68.9 million one year earlier. The wholesale and correspondent channels combined for 74% of non-QM originations, with the remainder coming through the retail channel.
In the first three quarters of 2017, Impac originated $656.2 million of non-QM loans, with a weighted average credit score of 726 and a weighted average loan-to-value ratio of 64%. For all of 2016, it did $289.6 million in non-QM volume.
Originations of government-insured products increased year-over-year to $499.7 million from $439.2 million.
“Since the end of the third quarter, we have seen our non-QM and government production grow across all origination channels,” Impac Chairman and CEO Joseph Tomkinson said in a press release. “We still anticipate securitizing our non-QM production in the first quarter of 2018, which will be a significant milestone for the company.”
Impac had net earnings of $2.3 million in the third quarter, down from $16.5 million one year earlier. The drop in origination volume, combined with significantly lower gain-on-sale revenue ($42.5 million versus $113.2 million for the third quarter of 2016) and margins (204 basis points versus 268 basis points), were the primary causes.
Impac’s servicing portfolio increased 66% compared with the end of the third quarter in 2016, $15.7 billion from $9.5 billion as the company elected to retain more mortgage servicing rights.
As a result servicing fees increased to $8.5 million from $3.8 million. But because of prepayments driven by lower interest rates in the third quarter that affected the fair market value of the portfolio, it had a $10.5 million net loss on its MSRs.
“Prepayments in the servicing portfolio remain high, causing a write-down on the mortgage servicing assets. However, as our servicing portfolio continues to grow, it is generating significant and stable quarterly revenue, in excess of $8.5 million a quarter,” Tomkinson said.


