Redwood Trust is prepping its first residential mortgage-backed security of 2014, a $347.3 million deal, according to a presale from Fitch Ratings.
Three triple-A tranches under the REIT’s Sequoia platform account for $323.2 million of the RMBS. (For further breakdown, see Capital Structure at bottom of article).
The underlying collateral for the deal consists of 15- and 30-year fixed-rate, and 10-year adjustable-rate loans to prime borrowers. Only 3.2% of the pool consists of loans with a 10-year, interest-only (IO) period.
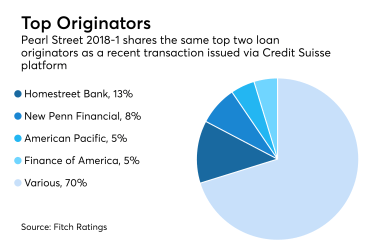
Among the five originators contributing the most volume to the pool, First Republic Bank accounted for 19.9% of the pool; Opes Advisors, 7.3%; JMAC Lending, 6.2%; Amerisave Mortgage Corp, 5.8%, and PrimeLending 5.3%.
The pool has a weighted average loan-to-value ratio of 67.5% and has more seasoning than recent Sequoia deals. The average FICO score — while still quite high at 765 — is lower by 1-10 points than the last three issuances of the trust.
A low LTV and high FICOs helps mitigate the risk associated with, among other things, high geographic concentration. California is home to 52% of the properties securing the underlying mortgages.