At PennantPark, Art Penn says volatility turns investors’ attentions to middle-market CLOs
Despite perceptions that smaller companies are riskier, they pose less risk to investors. Realized loss rates are lower, and they deliver higher returns.
The U.S. economy is relatively insulated from the events unfolding in Eastern Europe. Western Europe may be affected indirectly by higher energy prices.
The transaction, expected to close on March 2, has a non-call period end date of two years from the expected closing, a reinvestment period end date of April 15, 2026.
A broader investor base, rising inflation and higher interest rates are likely to result in significant demand for CLO bonds, which have experienced few defaults.
Deerpath’s average portfolio turnover rate of 37.8% over the past 12 months was higher than the 25.3% of all CLO 2.0 transactions.
While the indicative portfolio has an average credit quality of ‘B’ or ‘B-,’ Fitch also points out that the class A-1 notes have a 43.0% credit enhancement level.
The size of the current deal stems mostly from the ‘AAA’ piece, which was $210 million, compared to $162 million in the last ABS. Earlier deals hovered around $250 million.
Collateralized loan obligations may have to wait until 2022, because the market is seeking price discovery — but has little incentive to jump first.
One issuer says inclusion of enhanced reporting is the first step toward putting the entire RMBS platform on the blockchain.
BDS 2021-FL9 is allowed to be fully collateralized by multifamily or manufactured housing properties, although it has concentration limits on other property types.
The July 21‘Risk Alert’ brings practices most common to hedge fund managers under scrutiny, but CLO managers who replicate those practices should also take heed.
In a move becoming more commonplace for CRE CLOs, the collateral manager can direct modifications that are not subject to servicing standards in deal documents.
The Loan Syndications and Trading Association alerts market participants to the challenges of term-SOFR transition before year-end.
High CLO volume stems partly from transactions whose refis or resets anticipated last year were deferred when spreads widened considerably amid the pandemic.
Virtually the whole collateral pool will be comprised of senior secured loans, cash and eligible investments ultimately benefiting software, hotel and leisure.
Henry Brigham, Willis Hwang and David Knecht bring a combined 43 years of corporate trust experience to the Wilmington Trust team.
Similar to other CLOs, Golub 54 has a reinvestment period of four years, with a two-year non-callable period.
Issuers of leveraged loans appear ready to use SOFR, the popular alternative to LIBOR, putting leveraged loans a step ahead of the market.
Auto and credit card securitizations benefited from more rational consumer behavior, whole CLO issuance remained strong for both new issuance and refinancing deals.
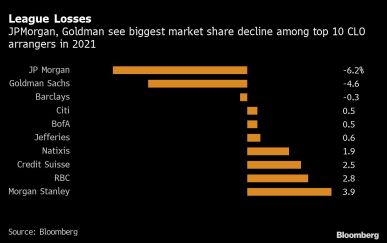
Goldman Sachs Group and JPMorgan Chase are ditching safeguards on credit lines to CLO managers, to defend their market share as arrangers in the lucrative business.
Couldn’t load more articles. Try again.