The government-sponsored enterprises transferred $5.5 billion of credit risk on $174 billion of mortgages in their portfolios during the first quarter, according to a Federal Housing Finance Agency Report.
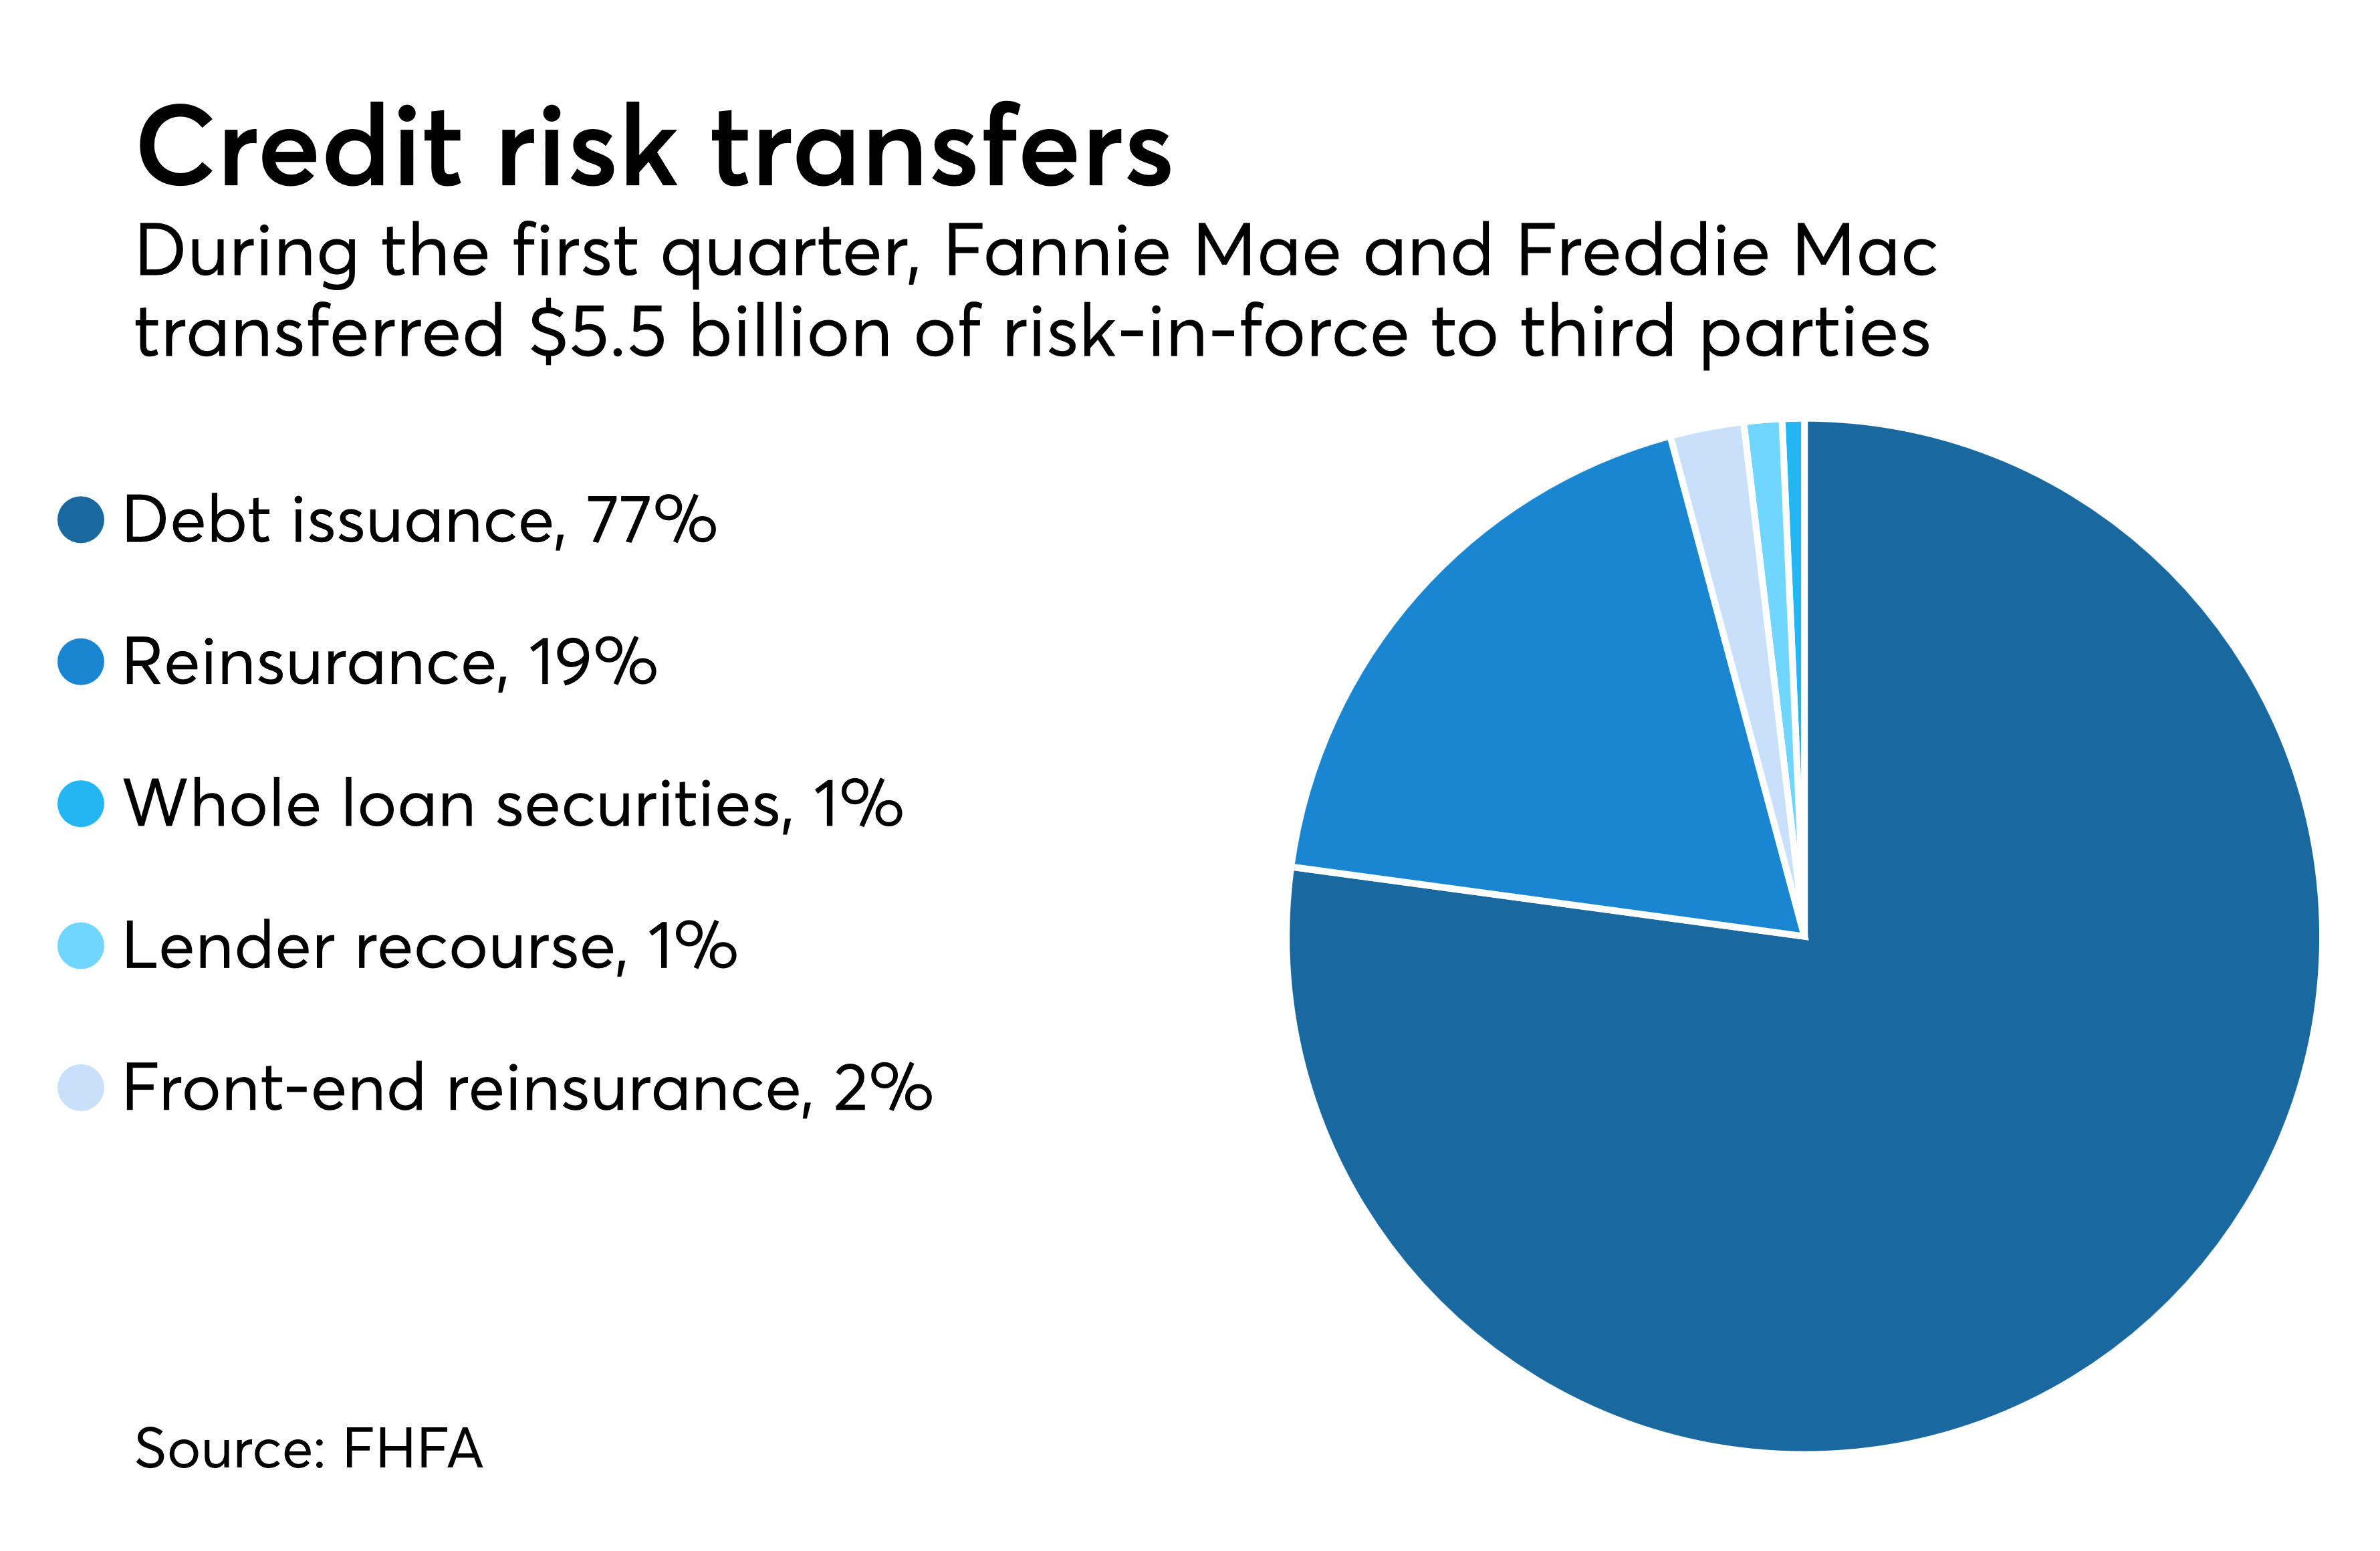
Debt issuances from the agencies were the primary risk transfer method. That was used for loans with $147 billion of unpaid principal balance, with a third party assuming risk-in-force of $4.2 billion.
Fannie Mae and Freddie Mac entered into reinsurance transactions on $20.4 billion of unpaid principal balance with risk-in-force of $1 billion.
Front-end reinsurance transactions were the next largest category of credit risk transfer, consisting of loans having $4.9 billion of unpaid principal balance and risk-in-force of $126 million.
Last September, Freddie Mac announced it was starting a front-end reinsurance pilot program that would last into February with unnamed private mortgage insurers that was expected to transfer $100 million of risk on $4 billion of new originations during the life of the pilot.
During the quarter, front-end reinsurance transactions made up $1.2 billion of Freddie Mac’s total, with $31 million of risk-in-force transferred.
Several weeks after Freddie Mac, Fannie Mae revealed its own pilot program that would run for a six-month period to transfer $13 million of risk on $3.7 billion of newly originated mortgages. By the end of the first quarter, Fannie Mae had transferred risk on $3.7 billion of loans in total, the report said.
Freddie Mac issued whole loan securities for $640 million of unpaid principal balance with $38 million of risk-in-force, while Fannie Mae did lender recourse transactions on $488 million of loans with $65 million of risk-in-force.
Total CRT activity from Fannie Mae was $108 billion, while for Freddie Mac it was $65 billion.
Private mortgage insurance, the primary form of credit enhancement used on mortgages sold to the GSEs with loan-to-value ratios over 80%, provided coverage on $48 billion of mortgages the agencies purchased during the quarter, providing risk-in-force of $12 billion.