First Help finances subprime auto pool with $239.7 million
FHF sources almost all its loans—most recently 96% in 2024—from franchise dealers.
© 2026 Arizent. All rights reserved.

FHF sources almost all its loans—most recently 96% in 2024—from franchise dealers.
The deal is structured as a public securitization, under Rule 144A, and is supported by lending indirectly through more than 1,100 partnerships across the country.

The United Auto 2025-1 series of notes has a more mixed subordination element compared with the previous deal.

Lendbuzz sells the notes as it juggles mixed performance results from 2023. Originations and revenues saw huge jumps, but so did operating expenses.

The current levels of credit enhancement are a reduction from levels of 58.0%, 48.7%, 35.9%, 22.5% and 17% on the classes A, B, C, D and E on the BLAST 2024-1 deal.
Initial overcollateralization is 11.3%, up from 8.50% of the initial collateral pool balance. Aside from that adjustment, target overcollateralization is 22.45%, compared to 13.00% on Westlake 2023-4 deal.

Issuance has been scant since DRIVE 2021-3 closed in November 2021. A lack of comparison deals from recent years makes it more difficult to forecast losses.

COVID-19 largesse enabled subprime borrowers to pay down debt and boost credit scores. Then interest rates rocketed up in 2022, and new subprime auto borrowers felt the pinch.

Classes A, B and C benefit from hard credit enhancement levels of 60.80%, 42.80% and 24.57%, respectively, an increase from the comparison deal.

Ratings analysts say the A1 through A3 tranches benefit from total hard credit enhancement of 43.00% of the deal's initial principal balance, which includes subordination and a non-declining reserve account of 1.00%.

The company is coming off of a recent period of performance improvements, with gains in net income, cash and cash equivalents.

In one of the deal's positive credit attributes, none of the underlying loans in the collateral have terms longer than 72 months. Such longer-term loans have historically performed worse than shorter-term loans.

As interest rates rise and delinquencies among borrowers with poor credit scores soar, investors are increasingly scrutinizing the riskiest slices of asset-backed securities sold by some subprime auto lenders. That's forced certain issuers to postpone deals or sweeten terms.

DriveTime's latest has initial hard credit enhancement that ranges from 55.70% for the class A notes to 15.40% for the class E notes, and the company just bumped up its warehouse commitment.

A vast majority of the collateral, a combined 82.73%, have terms of between 49-60 months (58.46%) and 61-72 months (24.27%), while a slight majority of the pool (51.66%) have no credit scores.

The subprime auto lender has a good track record, but there are concerns about used-car prices normalizing, according to KBRA.

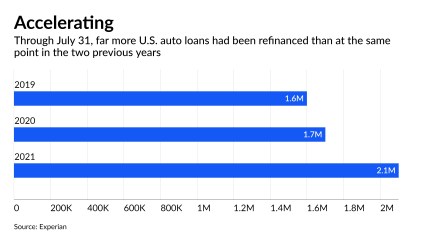
Subprime borrowers whose credit scores have risen since they bought their cars are increasingly looking for a better deal. Credit unions and small banks are seizing the opportunity, often with the help of fintechs.
The Spanish bank’s U.S. holding company said it will pay a premium to purchase the publicly traded shares in Santander Consumer Holdings. The proposal is subject to the approval of the auto lender’s board of directors.
A pool of subprime auto loans, new and used, and approved with a heavily automated, technology driven and multi-step process underpin a $559 million deal.

Carvana Auto Receivables Trust 2021-N2 is the used-car retailer's ninth securitization since 2019, and the third to include a pool exclusively made of non-prime loans.

Couldn’t load more articles. Try again.