Angel Oak reverts to in-house origination for next nonprime RMBS
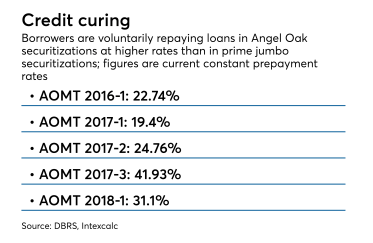
Similar to the sponsor's prior transaction, however, the collateral includes a large portion of loans underwritten using bank statements to verify borrower income: 49%.

© 2026 Arizent. All rights reserved.

Similar to the sponsor's prior transaction, however, the collateral includes a large portion of loans underwritten using bank statements to verify borrower income: 49%.
The investors initially won the right to sue as a group in 2015 before an appeals court reversed the ruling; the $13 billion lawsuit can now proceed as a class action.
Westlake increased the size of all eight classes of notes by at least 37% as investor demand surges for subprime ABS paper

Westlake's $800 million offering features increased exposure to loans sourced through a relationship with Ally Bank; CAC's $398 million deal is notable for having less seasoned collateral.

The online small-business lender was aided by loan growth, wider margins and stable credit trends. Its shares surged by 25% after second-quarter earnings were announced.
Conn’s has increased the credit enhancement on its latest consumer loan securitization to account for rising losses on its managed portfolio, according to rating agency presale reports.

Loans backing the $1.2 billion AmeriCredit Automobile Receivables Trust 2018-2 have the highest weighted average FICO score in the history of the platform.

The bulk of the collateral, 59.6%, was acquired from Impac Mortgage Corp., a lender with a long track record; the remainder, 40.4%, from Sprout Mortgage Corp., a relative newcomer.

The credit quality of the initial collateral pool is similar to that of United Auto Credit Corp.'s previous transaction, but the performance of the lender's managed portfolio of subprime loans is improving.

Kroll Bond Rating Agency says the riskiest notes issued in the 2016 transaction are at “substantial risk of loss,” following on the heels of a similar move by S&P last week. Kroll also put a more senior class of notes under review for a possible downgrade.

S&P has cut its credit ratings on a deep subprime loan securitization completed by Honor Finance in 2016, warning that the most subordinate tranche of notes issued in the deal is “at risk of not being repaid.”

OneMain can add qualifying loans to the pool of collateral for the first two years of the transaction; by comparison, its two prior deals featured one-year revolving periods.

The Dallas-based lender's third foray into the deep subprime ABS market in 2018 arrives as recent Santander DRIVE securitizations are performing well with recently lowered loss expectations from S&P Global Ratings.

Loans originally securitized in three 2013 transactions account for some 11.4% of the initial collateral for the $230 million CPS Auto Receivables Trust 2018-C, according to S&P Global Ratings.

The notes, which are rated by DBRS, are backed by a mix of products to borrowers with weak credit; the pool of collateral will revolve over the first two years of the transaction.

Lauren Hedvat, Angel Oak's managing director of capital markets, said that the rising non-qualified mortgage volume in the market has expanded the number of third-party origination loan packages for purchase.
In Santander Consumer USA's third subprime shelf offering of 2018, new cars represent 55.8% of the collateral. In previous deals dating to 2013 new-car concentrations did not exceed 40.9%.

Global Lending Services returns to double-A status in its new $299.4M transaction, while American Credit Acceptance issued another AAA-rated deal with a substantial prefunding account feature.

Despite a steep drop in average FICO and increase in extended-term loans, DriveTime is shaving overcollateralization levels thanks in part to improved performance from its outstanding securitization portfolios.

The borrowers behind the $401.6 million COLT 2018-2 have weighted average liquid reserves of $426,633, or nearly twice the level of borrowers backing a deal completed in January.
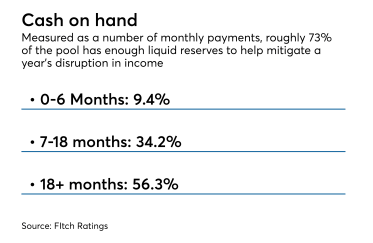
Couldn’t load more articles. Try again.