Modernized credit scores gain traction despite operational hurdles
As lenders explore the adoption of FICO 10T and VantageScore 4.0, setbacks and data limitations remain.

© 2026 Arizent. All rights reserved.

As lenders explore the adoption of FICO 10T and VantageScore 4.0, setbacks and data limitations remain.
The move comes about a year after rising delinquency levels prompted SBA to raise lender fees and tightened underwriting standards in its flagship 7(a) program.
Sens. Ed Markey and Ron Wyden argue that the Small Business Administration neglected to warn small firms of the risks of merchant cash advances and closed off a key "escape route" from the resulting debts.
Standard & Poor's found modeled foreclosure frequency and loss coverage to be in similar ranges as classic FICO but showed concern about potential bias.

House lawmakers modified a ban on big-money investors from purchasing single-family homes, broadening the exemptions for build-to-rent properties and eliminating requirements in a Senate version of the bill that affected investors divest their holdings.
Serious delinquency transitions in older mortgages inched up, hinting at the impact of an FHA rule change's impact in conjunction with other stressors.
Consumer Credit Portfolio II is not a securitization, but Groundfloor is known for two deferred-pay residential transition loan ABS that are paying investors higher premiums than rated RTLs.
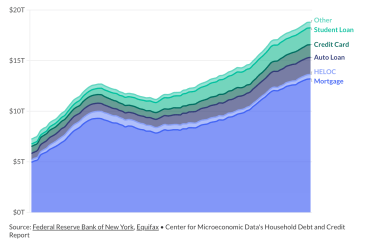
The 90-day-plus delinquency rate on student loans hit 10.3% in the first quarter, and New York Fed researchers warn that a second wave of defaults could be coming. Evidence is mixed regarding the likely impact on other consumer-lending segments.
The transaction comes to market with initial hard credit enhancement levels of 33.60%, 22.90%, 13.50% and 8.65% across the subordinate tranches, higher than the previous deal.

Kapitus funds receivables through two revolving securitizations totaling $575 million, and a $230.1 million warehouse line of credit from Truist, which matures in June 2027.

Borrowers in the pool had a non-zero weighted average credit score of 608, with a 112.12% loan-to-value (LTV) ratio.

Despite market volatility from the conflict–added to tariff impacts–credit portfolio managers see liquidity as steady, with no significant signs of stress.

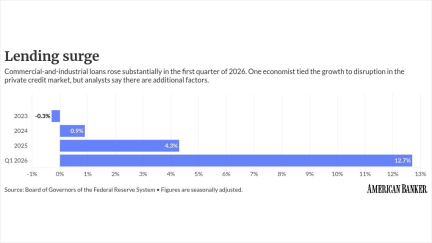
The recent uptick in commercial-and-industrial lending is the result of disruption in the private credit sector, one economist argues. Bank analysts say the upheaval in private credit is one factor among many.
The Consumer Financial Protection Bureau finalized a new version of a small-business lending rule that took 17 years to get over the finish line. Banks are still lobbying for the rule to be repealed.
The weighted average, base-case annualized gross loss declined from 11.78%, from 11.86%, because of minor changes in its assumptions of pool segment defaults.

The three class A notes, A1, A2 and A3, of GCAR 2026-2 notes will all benefit from hard credit enhancement levels, plus haircut to excess spread of 56.07%.

The credit startup is seeking a limited-purpose charter from federal regulators through the Competitive Equality in Banking Act's credit card bank carveout.
Nationwide, Americans are falling behind on their car loans. But among Ally Financial's customers, delinquencies fell during the first quarter.
Analysts expect the pool to be composed of receivables primarily from franchise dealers that offer indirect financing to consumers often overlooked by traditional financing sources such as banks.

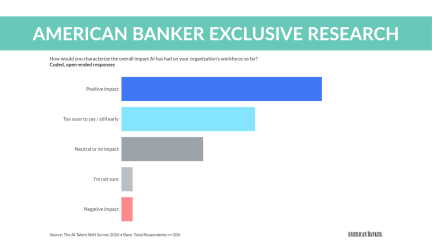
American Banker data found that those who upped artificial intelligence spending by more than 25% in the last year saw major improvements in employee output.
Couldn’t load more articles. Try again.