FHA addresses pain point for servicers after court ruling
The Federal Housing Administration's clarification addresses interpretations of an 8th U.S. Circuit Court of Appeals decision that increased industry costs.
© 2026 Arizent. All rights reserved.

The Federal Housing Administration's clarification addresses interpretations of an 8th U.S. Circuit Court of Appeals decision that increased industry costs.
Levels of home equity in seriously delinquent loans have fluctuated but today there's still a sufficient amount to help many access foreclosure alternatives, Intercontinental Exchange said.
But the volume of activity for distressed properties is still lower than the historic norms, Attom Data Solutions said.
Over one-third of the struggling borrowers who received recast loan terms in the first quarter cut their monthly obligation by 20% or more.

New starts surged 75% compared to a year ago, but repossessions saw their first decline in one-and-a-half years, according to Attom.
But late borrower payments slightly grew in November, with 18 metro areas reporting an increase, up from six metro areas in October, CoreLogic's report found.
The measure enacted on Dec. 30, 2022 applies retroactively and could add servicing risks that lending divisions will likely consider in underwriting and pricing on new loans originated in the state.
Three percent of all mortgages were 30 or more days past due on their scheduled payment or in foreclosure in July.
The month ended with 54,000 less properties for which the borrower was at least 30 days or more late on their payments, Black Knight said.
Still near historic low levels, the share of borrowers entering the early stages of delinquency in June increased 0.1 percentage point.
Completions in August remained far lower than before COVID-19 arrived in the United States but initial actions rose fast enough to potentially meet expectations that they'll normalize in 2023.
At the same time, the share of overall vacancies fell due to limited inventory, according to a new Attom report.
Inflation and higher interest rates are hurting distressed borrowers, but low unemployment, remaining forbearance and loss mitigation options are still blunting their impacts, recent loan-performance numbers suggest.
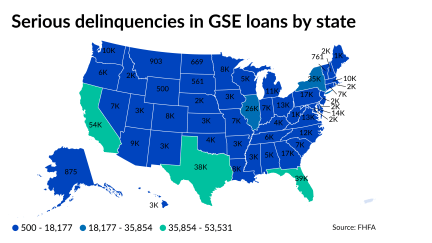
The government-sponsored enterprises divested themselves of the largest share of these loans since they first began selling them in 2014, a Federal Housing Finance Agency report found.
But a slower-than-anticipated rate of repossessions suggest distressed homeowners are finding solutions.
Strong general unemployment gains, student loan deferrals and borrowers enjoying low interest rates secured in the refinance boom contributed to the positive gains.
While smaller in number, initiated foreclosures had a similar consecutive-quarter gain as the market transitioned away from pandemic-related relief that has artificially constrained workout activity.
Meanwhile, 707,104 mortgages remain in forbearance, accounting for a combined $136 billion in unpaid balances.
However, the serious delinquency rate dropped to a point significantly below the market-wide average, and much of the foreclosure activity allowed to proceed did so with new consumer protections in place.
However, the seven institutions in the Office of the Comptroller of the Currency study service 13% fewer loans compared with the third quarter of last year.
Couldn’t load more articles. Try again.