J.P. Morgan’s jumbo mortgage pool raises $391.5 million in RMBS
The deal structure includes a lock-out feature that will redirect the portion of the subordinate principal among other protective features like subordination.

© 2026 Arizent. All rights reserved.

The deal structure includes a lock-out feature that will redirect the portion of the subordinate principal among other protective features like subordination.
Despite a limited representation and warranty framework, the entire pool has experienced third-party due diligence, which reduces the risk of future violations.

The transaction uses a shifting interest repayment structure, and its lockout that is subject to performance triggers.
The deal is the seventh prime jumbo issuance from Chase Home Lending Mortgage Trust in 2025.
Easing regulations on the GSEs will likely drive elevated activity in non-QM if or when it occurs, leaders at the real estate investment trust also said.

The senior certificates get credit protection from a specified lockout period, when the subordinate classes will receive no unscheduled principal payments from the collateral mortgages.

SEMT 2023-2 shifted some of its underwriting from traditional full documentation to agency underwriting, with the latter accounting for 14.1% of the pool balance.

The entire pool is comprised of fixed-rate, fully amortizing mortgages, with an average balance of $901,373. They are also first-lien loans.
All but 501 of the loans in the pool were assessed following the new general QM rule. Otherwise, the pool is largely comprised of jumbo, prime loans.

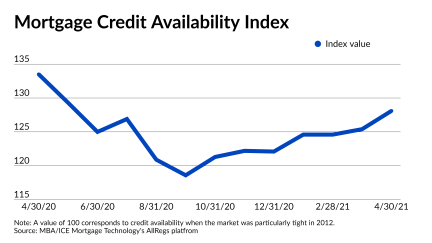
It’s getting easier to close bigger loans for higher-priced properties, but credit is expanding slower for first-time buyers.
Upcoming changes to underwriting regulations, as well as the end of the QM patch, in addition to growing home values, all add up for this market to have a good year.
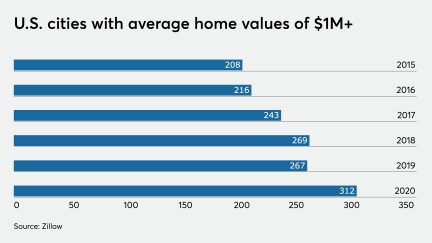
The pool of 359 loans also on average carry higher balances (over $900,000) compared to the REIT's earlier pass-through deal this year.
But existing deals are likely to experience issues resulting from higher defaults, faster prepayment speeds.
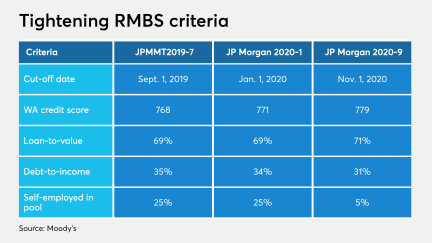
Lenders also increased jumbo product availability as well as rolling out new SOFR-indexed ARMs.
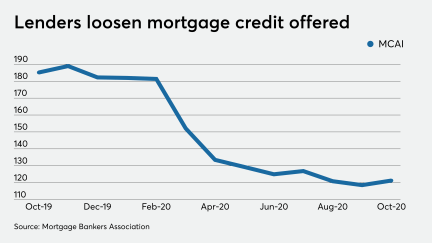
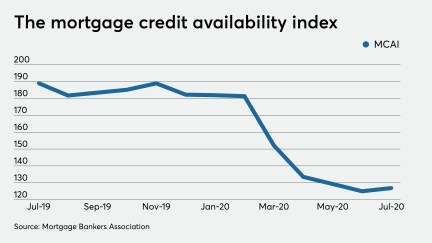
Conditions have improved for the first time since November.
However, those who aren't current bank customers need to have $1 million in a qualifying account.
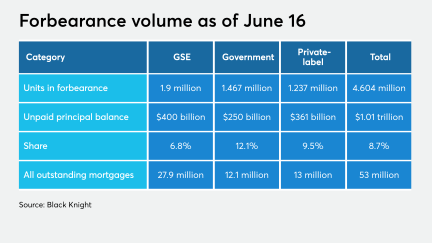
Compared with the week prior, approximately 57,000 fewer loans from all investor types were forborne.
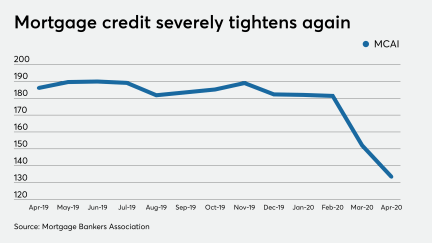
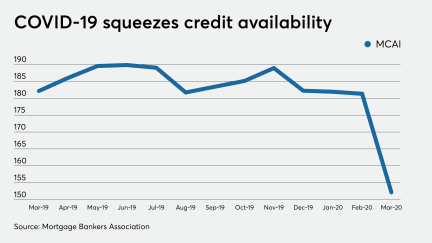
Many originators stopped making riskier products, including jumbo loans and low credit score offerings, during April.
The Federal Reserve's $2.3 trillion loan stimulus includes plans for outstanding commercial mortgage-backed securities and newly issued collateralized loan obligations.
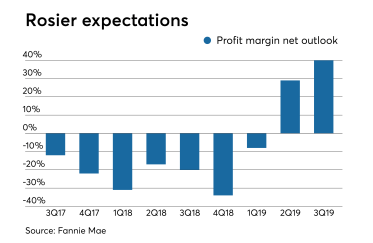
A swell of refinance demand amid a low mortgage rate environment pushed lender profit margin outlooks to the highest level since the first quarter of 2015, according to Fannie Mae.
Couldn’t load more articles. Try again.