RMBS issuance should continue to slide in 2024, S&P says
High interest rates and constrained inventory will take its toll on originations and securitization activity in 2024, the rating agency commented.
© 2026 Arizent. All rights reserved.

High interest rates and constrained inventory will take its toll on originations and securitization activity in 2024, the rating agency commented.
Though home mortgage issuance has slumped in line with originations, new potential bank capital rules and increased consumer debt consolidation could boost activity for these two subsets in the secondary market.
“One” is the first in a series of non-agency mortgages the wholesaler plans to introduce this year.
However, the share of new impairments increased, likely as a result of the high concentration of these loans given to self-employed borrowers.
Upcoming changes to underwriting regulations, as well as the end of the QM patch, in addition to growing home values, all add up for this market to have a good year.
The transaction features a pool of non-qualified mortgages with a higher-than-average delinquency rate driven by COVID-19 relief plans.
Wells Fargo is exploring selling a unit offering store-branded credit cards as the bank chooses businesses to keep or break off in a broad strategic overhaul, according to people with knowledge of the matter.
As COVID-19 infections increase across the country, including in California, Citigroup has structured a residential mortgage-backed securities offering fit for the times, providing investors with a strong deal structure and robust collateral.

On the heels of its first CLO transaction this year, Western Asset Management is back in the market with a $355.72 million private-label RMBS offering in which a tenth of the borrowers have been granted forbearance.
Vista Point Mortgage is aggregating a collection of mostly non-conforming mortgages that it acquired from several originators.
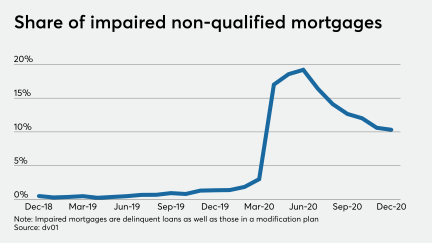
An early look at securitized residential home-loan performance amid the coronavirus pandemic indicates encouraging trends thus far in impairment levels of non-qualified mortgages, according to a new report from investor analytics firm Dv01.
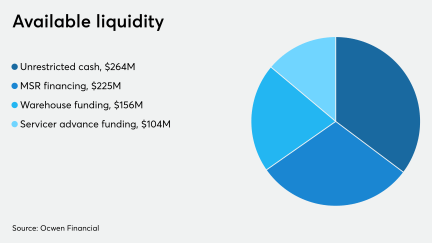
Ocwen Financial has approximately $749 million of liquidity from various sources to deal with servicing issues arising from the coronavirus, a company press release said.
The two deals continue a late-year surge of private-label RMBS deal volume totaling $8.37 billion priced since Oct. 1.
Lenders have bundled more than $18 billion worth of non-QM, private-label loans into bonds this year that they then sold to investors, a 44% increase from 2018 and the most for any year since the securities became common post-crisis.
With prospects for government-sponsored enterprise reform improving, players in the private residential mortgage-backed securities market are starting to think about how they could better compete against the GSEs while awaiting change.
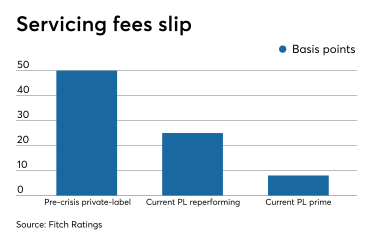
Private-label mortgage securitizations with variable servicing fee arrangements could become more common going forward as issuers look to increase investor cash flow while reducing the loan servicer's economic exposure, Fitch said.
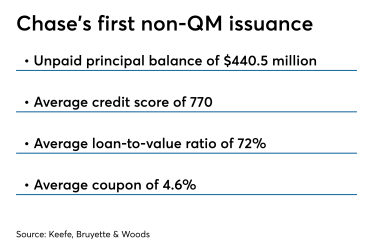
Non-qualified mortgage-backed securities record issuance in the first quarter puts it on pace to top full-year volume predictions, according to Keefe, Bruyette & Woods.
Liquidity, products and pricing are the main concerns for the secondary mortgage market in 2019.

Although forecasts anticipate a continuing drop in overall originations, private-label residential mortgage-backed securitizations backed by newer loans are expected to keep increasing through next year, according to Bank of America.
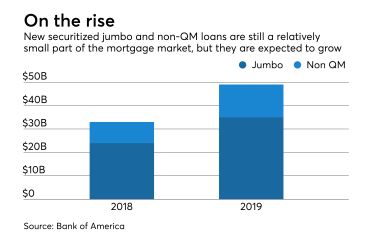
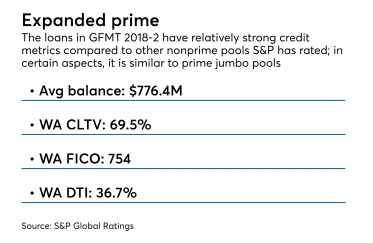
Rating agencies are sparring over a new feature in a private-label RMBS that upends the relationship between senior and sub bondholders.
Couldn’t load more articles. Try again.