Fed finalizes stress test reforms, takes comment on scenarios
The Federal Reserve voted 6-1 to finalize its proposed stress test reforms, including seeking input on stress test scenarios and models annually and averaging results over two years.

© 2026 Arizent. All rights reserved.

The Federal Reserve voted 6-1 to finalize its proposed stress test reforms, including seeking input on stress test scenarios and models annually and averaging results over two years.
Federal Reserve Vice Chair for Supervision Michelle Bowman Friday highlighted a pair of new provisions to the final stress test framework that arose from public commentary submitted to the agency last year.
Use of the instruments … is growing, and was equivalent to around 2% or less of total bank loans in the European Union, US, the UK and Canada at end-2024.

The Federal Reserve Friday issued a set of proposed changes to its stress testing program for the largest banks that would disclose the central bank's back-end stress testing models, a move that the Fed had long opposed out of fear of making the tests easier for banks to pass.
Federal Reserve Vice Chair for Supervision Michelle Bowman said in a speech Tuesday that the central bank would unveil proposed revisions to its stress testing regime "in the next week or so."
In a unanimous vote, the Board of Governors moved to lower Morgan Stanley's stress capital buffer requirement to 4.3%, down from a preliminary 5.1% based on this year's stress test results.
After passing the Federal Reserve's stress tests with high marks, large banks announced dividend increases. In some cases, they also said the Fed had conceded that certain prior calculations needed to be revised.
The largest U.S. banks took less of a capital hit under the Federal Reserve's hypothetical stress scenario than they did last year, but averaging the two sets of results could impact next year's regulatory requirements.
The Federal Reserve attributes the uptick in simulated losses in this year's stress test examination to heightened risks on bank balance sheets and higher expense levels. Credit cards and corporate lending were top areas of concern for the central bank.
The Federal Reserve vice chair for supervision says the failure of Silicon Valley Bank showed the shortcomings of the current stress testing regime.
On a combined basis, the GSEs performed better under this year's scenario than they did in 2021, but the Federal Housing Finance Agency said changes were still needed.

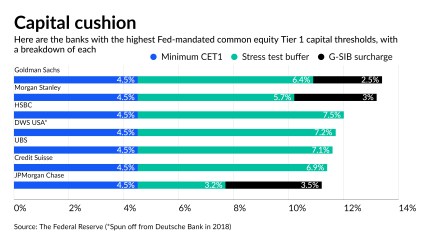
This year’s stress-test results show large banks have more than enough capital to deal with a major economic crisis, but their capital requirements will likely go up anyway. That has some observers and industry officials concerned credit will tighten even as the economy teeters on the edge of recession.
This year’s stress tests examined 23 banks including JPMorgan Chase and Goldman Sachs, with the remainder of the firms on an “every other year” test cycle. The capital requirements for those remaining firms are unchanged from last year.
Policymakers have eased some rules and the Supreme Court recently dealt a blow to the Consumer Financial Protection Bureau. But as the landmark legislation approaches its 10th anniversary, the post-crisis regulatory regime has stayed largely intact.
Unlike in previous years, the results from two different evaluations will be released simultaneously and will include an assessment of bank capital under coronavirus-related scenarios.
The general structure of this year’s reviews is unchanged despite the pandemic. But a supplemental analysis of banks' response to the downturn could weigh heavily in evaluating 2020 capital distributions and making adjustments to the tests over the long run.
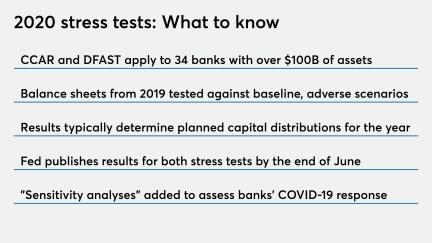
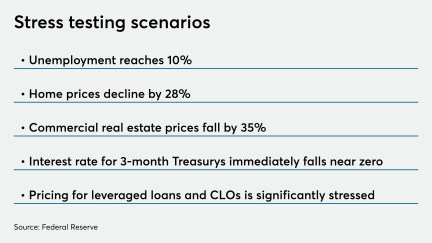
The Federal Reserve also said in a supervisory report released Friday that it would conduct stress tests this quarter as planned, taking into account sudden deterioration in the economy brought on by the coronavirus pandemic.
Regulators are alarmed about banks' rising exposure to high-risk corporate credits and want more data on how they would perform in a recession.
In a downturn, some fintechs, such as independent lenders, will be more vulnerable to economic forces than those working to service banks' regulatory needs.
As the central bank board proceeds with reforms easing the post-crisis regulatory regime, the Obama-appointed governor has not shied from opposing the agency’s course.
Couldn’t load more articles. Try again.