ARMs tripled at banks over past decade
Growth in conventional originations at U.S. banks came with the unexpectedly rapid rise of 30-year fixed interest rates in 2022, Federal Reserve researchers found.
© 2026 Arizent. All rights reserved.

Growth in conventional originations at U.S. banks came with the unexpectedly rapid rise of 30-year fixed interest rates in 2022, Federal Reserve researchers found.
The loans accounted for 18.6% of conventional single-family dollar volume in April, quadrupling its share of business at the peak of the refinance boom, according to Corelogic.
Consumers taking out adjustable-rate mortgages last year put down a median down payment of 23.6%, researchers at the real estate brokerage found.
The modifiable templates are a follow-up to a similar notification the organization created in 2019 for lender use.
Lenders also increased jumbo product availability as well as rolling out new SOFR-indexed ARMs.
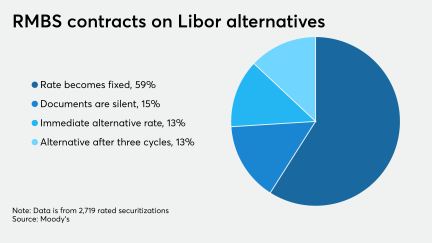
Bondholders could see principal losses if, due to the way the documents are worded, the rate is frozen at the last published amount.
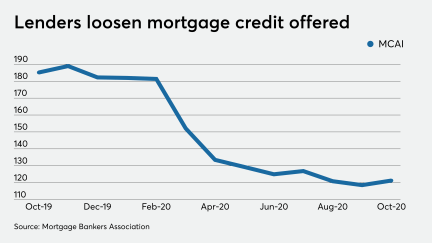
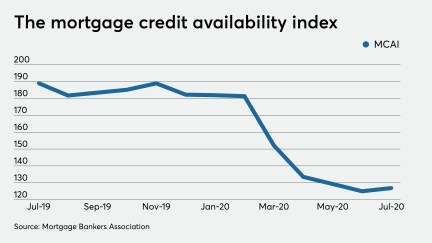
Conditions have improved for the first time since November.
The Consumer Financial Protection Bureau seeks to address challenged posed by the sunset of the London interbank offered rate at the end of 2021.
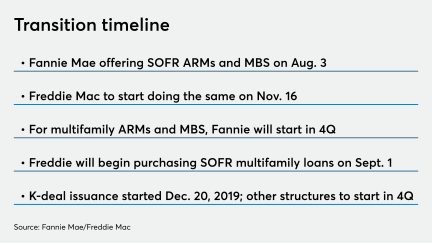
Fannie Mae and Freddie Mac have different timelines for the switch.
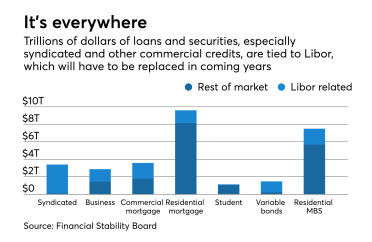
The biggest issuers of bonds tied to the benchmark tapped to replace U.S. dollar Libor are suddenly pulling back, a potential blow to efforts by regulators to wean the financial system off a much-maligned reference rate.
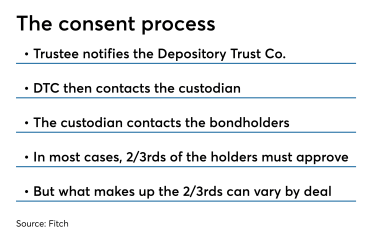
Trustees are concerned about obtaining proper consents from legacy residential mortgage-backed securities investors in a timely fashion in order to make the switch from Libor to another index, Fitch Ratings said.
The pool of 497 loans includes first-lien fixed- and adjustable-rate mortgages for single-family homes and multifamily properties, primarily underwritten to self-employed borrowers.
The Mortgage Bankers Association created a template for originators to notify new borrowers when their adjustable-rate mortgage switches to a different index once publication of the London interbank offered rate discontinues.
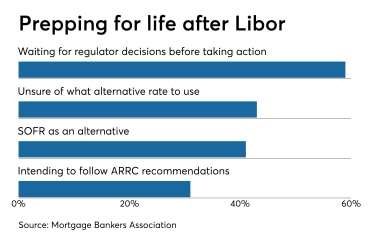
Commercial and multifamily mortgage lenders need to figure out their plan for replacing the London interbank offered rate index potentially expiring at the end of 2021.
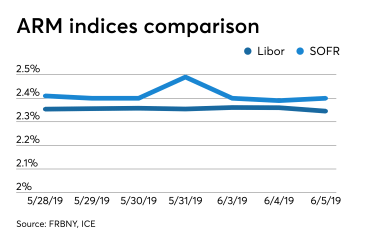
The Urban Institute's conclusion is based on estimates that one-year SOFR rates could be 25 to 50 basis points lower than the current Libor equivalent.

Fannie Mae has priced more securities that support a transition away from the London interbank offered rate.
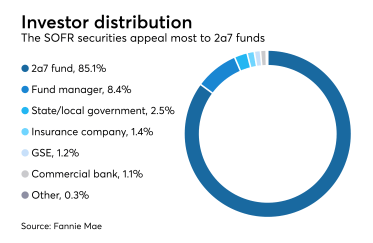
Fannie Mae has issued securities supporting the transition away from the London interbank offered rate; something that could become more pressing for lenders if adjustable-rate mortgages were to become more prevalent.
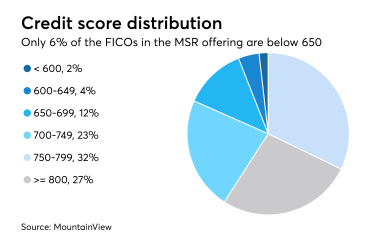
MountainView is brokering a nonrecourse $3.5 billion package of Fannie Mae and Freddie Mac mortgage servicing rights on behalf of an unnamed seller.
A Fed committee studying Libor’s replacement has dwelled heavily on the potential impact to the derivatives market. Loans may become a bigger part of the conversation later this year, but the panel plans to leave a lot of the specifics up to lenders.